

Cashew—Expense Budget Tracker
4.7

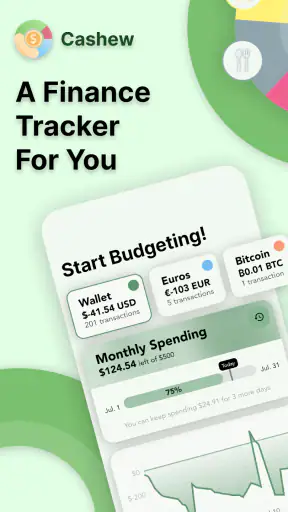
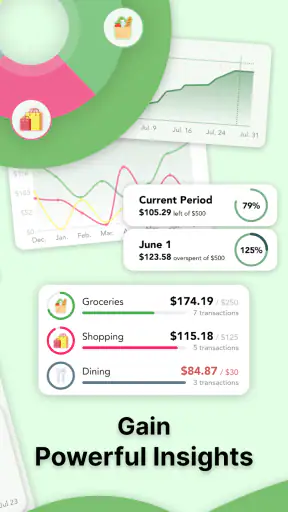
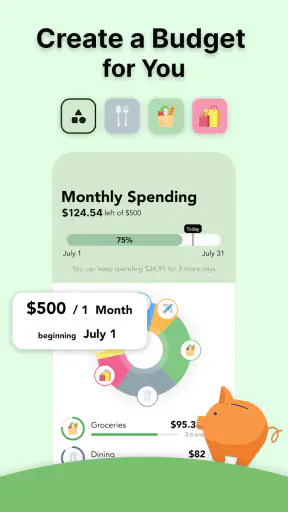
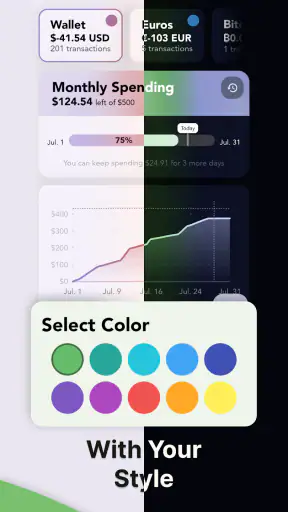
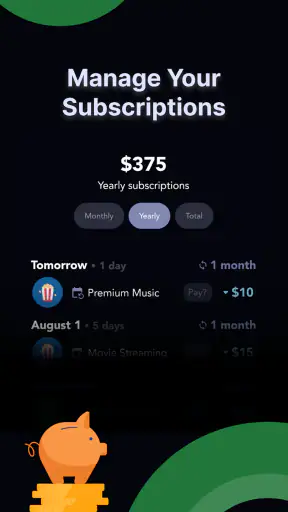
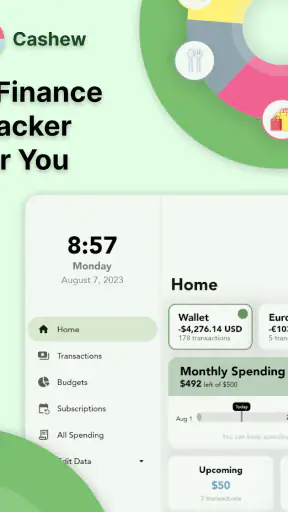
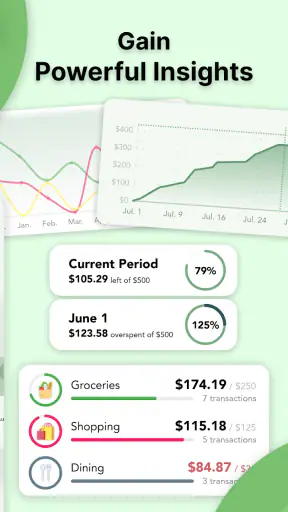
I like expense apps that make me think less, not more. Cashew—Expense Budget Tracker takes that approach by putting everyday spending at the center of the experience. It is a finance app from Dapper App Developer, available for free to users aged Everyone, and its main appeal is easy to understand: record what you spend, give it some structure, and use that record to make better decisions before the month disappears.
After using it as a personal spending companion, I found its most important capability is not simply entering purchases. The real value is turning small transactions into a visible pattern. A coffee, a grocery stop, a subscription, or an unexpected repair can feel harmless in isolation. Once those expenses are grouped and reviewed together, they become much easier to judge. That shift is what makes the app useful beyond being a digital notebook.
The app has built a strong audience, with an average rating of 4.7 from around 27 thousand ratings and more than 500 thousand installs. Those figures suggest that its straightforward idea connects with many people, but they do not remove the need to decide whether its style suits you. Cashew is best understood as a hands-on tracker for people willing to enter and review their own spending, rather than as a completely automatic financial dashboard.
Why the central tracking idea matters
Most people do not need a complicated financial system to discover that they are overspending. They need a reliable way to notice it early. Cashew focuses on that moment between making a purchase and understanding its effect on the rest of the month. By keeping expenses in one place, it gives me a better chance of spotting repeated habits before they become a problem.
That makes the app particularly useful for variable spending. Fixed bills are usually easy to remember because they arrive on a schedule. Flexible costs are different. Food delivery, transport, entertainment, small shopping trips, and cash purchases can quietly consume the money that was supposed to cover them. A tracker helps because it gives those less predictable expenses a visible shape.
I also appreciate that this kind of tool can support a modest goal without requiring a complete lifestyle change. You do not have to become an expert in personal finance. You can begin by recording purchases consistently, then look for one category that deserves attention. The practical lesson is often not “cut everything,” but “understand which repeated choice is making the month tighter.”
The app’s store summary describes it as an expense tracker designed for you, while the short description simply presents the name Cashew. In practice, that simplicity is part of the appeal. It does not force the reader to learn a financial vocabulary before getting started. The useful question is immediate: what did I spend, and how does it fit into my plan?
Entering an expense is only the first step
When I use a tracker, the quality of the result depends heavily on the habit of recording transactions close to the time they happen. Waiting several days creates gaps, and gaps make the final picture less trustworthy. Cashew works best when I treat it as a quick checkpoint after a purchase rather than as a monthly chore.
A good routine is to enter spending after leaving a shop, finishing a meal, or receiving a digital receipt. If that is not practical, I would set aside a short moment in the evening and record everything while the details are still fresh. The important point is consistency. A beautifully organized budget with missing purchases is less useful than a simple record that reflects real life.
I would also avoid creating too many categories at the beginning. Detailed labels can look attractive, but they make entry slower and encourage abandonment. I prefer starting with broad groups that answer useful questions: where is most of my flexible money going, and which area should I review? Once the habit is stable, more detail can be added where it genuinely changes a decision.
This is one of the less obvious trade-offs of a manual expense tracker. The app can make spending clearer, but it cannot make the user’s input accurate by itself. People who expect every transaction to appear automatically may find this approach demanding. People who want to stay aware of each purchase may find the same manual step helpful, because it creates a small pause before spending becomes invisible.
A realistic week with Cashew
Imagine someone who receives income at the start of the month and knows the major bills already. The difficulty is everything around them: lunches during workdays, occasional rides, household items, and social plans. On Monday, recording a small lunch may feel unnecessary. By Friday, several similar entries reveal a pattern that memory would probably underestimate.
At that point, the app becomes more than a list. The user can ask whether the issue is the amount of each purchase or how often it happens. Those are different problems. If individual meals are reasonable but frequent, the solution might be planning food before leaving home. If one large purchase caused the pressure, the better response may be adjusting the timing of a nonessential expense. A useful tracker supports that distinction.
For a couple or household, the same method can help during a weekly money check-in. One person can explain an unfamiliar transaction, while both look at the overall pattern rather than arguing from memory. I would not treat the app as a replacement for a shared financial conversation, but it can give that conversation something concrete to discuss.
Another practical use is preparing for an irregular month. Before a holiday, move, school term, or large annual payment, reviewing recent spending can show which flexible areas have room to move. The benefit is not perfect prediction. It is reducing surprise by using actual behavior as a starting point.
The best workflow for getting useful results
I recommend a three-stage routine. First, record expenses with enough detail to recognize them later. Second, review the entries at a regular point in the week, when there is time to notice patterns. Third, make one small adjustment rather than setting an unrealistic collection of rules. This keeps the app connected to decisions instead of turning it into a filing cabinet.
A useful tip is to distinguish between a one-off exception and a repeating habit. A birthday gift should not automatically lead to a permanent spending restriction. A daily convenience purchase probably deserves more attention if it appears again and again. Looking for repetition prevents the tracker from encouraging overreactions to unusual events.
Another tip is to use the app before a spending decision, not only afterward. If I am deciding whether I can afford a discretionary purchase, reviewing recent entries can provide a more honest answer than checking the bank balance alone. The bank balance may include money already needed for bills. A spending record helps separate available money from money that merely happens to be present.
I would also review the app when a budget feels unrealistic. If a category is repeatedly exceeded, the answer may not be stricter discipline. The planned amount may simply be disconnected from actual life. A realistic budget should challenge me without pretending that normal expenses do not exist. Cashew is valuable here because repeated entries can expose the difference between an intention and a workable plan.
Where it compares well with usual alternatives
Compared with a paper notebook, Cashew is easier to review because digital records can be kept together and revisited without carrying a separate ledger. Compared with a basic notes app, it is designed around expense tracking rather than leaving the user to invent a format. That focus matters when I want a repeatable routine instead of a collection of inconsistent notes.
Compared with a spreadsheet, the app is likely to feel less intimidating for someone who does not enjoy building formulas or maintaining a personal accounting template. A spreadsheet can be more flexible, especially for unusual household arrangements or detailed long-term analysis, but its flexibility also creates work. Cashew is the better choice when the priority is regular use rather than designing a custom financial system.
Automatic bank-connected tools can be more convenient for people with many transactions or several accounts. They reduce manual entry, which is a genuine advantage. However, they can also make spending feel distant: transactions arrive in the background, and the user may review them only after money has already gone. Cashew’s hands-on approach is slower, but that friction can improve awareness for someone who wants to stay involved.
That comparison also explains when I would choose something else. If you need investment analysis, business bookkeeping, complex debt planning, or extensive account synchronization, a dedicated financial platform may be more appropriate. Cashew’s strength is the everyday expense habit, not replacing every financial tool a household or business might need.
Small frictions that affect long-term use
The main limitation is the responsibility placed on the user. Missed entries weaken the picture, especially for cash spending or purchases made across several payment methods. Anyone who dislikes manual tracking may start enthusiastically and then stop once the novelty fades. I would test the routine for a couple of weeks before relying on it for serious budgeting decisions.
There is also a difference between seeing spending and changing it. The app can help reveal a pattern, but it cannot decide which trade-off is right for your life. A high food budget might reflect health needs, a demanding work schedule, or caring responsibilities. Cutting it without context would be poor advice. The app is most useful when its information is interpreted with common sense.
The free price makes trying it easy, although in-app purchases range from $1.49 to $19.99 per item. That does not automatically make the paid options worthwhile for everyone. I would first establish whether I actually use the core tracking workflow regularly. If the habit does not stick, extra spending on optional functions will not solve the underlying problem.
Cashew supports devices running Android 7.0 or later, and the current version is 6.6.11. For most people considering it on a compatible Android phone, the more important question is not technical eligibility but whether they are comfortable with the app’s active, user-maintained style. The age rating is Everyone, so the presentation is suitable for a broad audience, though financial responsibility still depends on the person using it.
Who will gain the most from it
I would recommend Cashew to someone who often wonders where the month’s money went, especially when the problem comes from many modest purchases rather than one dramatic expense. It is also a good fit for students, first-time budgeters, people adjusting to a new income pattern, and anyone who wants a clearer view without learning spreadsheet techniques.
It can be especially helpful during a transition: moving to a new home, changing jobs, starting independent living, or trying to build a savings habit. During those periods, old assumptions about spending may no longer apply. Recording actual costs gives a faster reality check than relying on a budget copied from a previous stage of life.
I would be more cautious recommending it to a person who needs automatic importing as a non-negotiable feature, manages a complicated shared budget, or wants detailed financial forecasting. That user may become frustrated by the attention required for everyday entry. A bank-integrated or specialist accounting app could be a better match, even if it feels less personal.
One final question many people have is whether an expense tracker is worth using when their finances already feel simple. In my experience, simplicity is exactly when it can be easiest to build the habit. You do not need a complicated financial situation to benefit from seeing recurring choices clearly. The app earns its place when it helps answer a real question, such as whether a planned purchase fits comfortably or whether a recurring cost deserves review.
Another question is how often the app should be checked. I would not turn it into an anxious ritual after every transaction. Recording purchases promptly and reviewing the overall picture once a week is a sensible balance for many users. The goal is awareness that supports decisions, not constant judgment over every small expense.
After using it, my view is that Cashew succeeds because it keeps the central action understandable: capture spending, look for patterns, and adjust deliberately. Its strongest feature is also its defining limitation. Manual involvement can feel like work, but it makes the user face each expense instead of waiting for an automated report to explain the damage later.
For me, that makes it a worthwhile free finance app when the goal is everyday control rather than advanced accounting. I would start with a few broad categories, record purchases for a full routine, and review repeated behavior before making changes. If that process feels useful, the app can become a steady financial check-in. If manual entry feels unbearable, I would choose an automated alternative instead. The right choice depends less on how sophisticated the tool looks and more on whether its workflow is one you will actually keep using.
4.7
672.00 Reviews
Pros
- Clean interface makes daily expense tracking quick and easy.
- Supports custom categories for more accurate spending organization.
- Budget limits help monitor progress before overspending occurs.
- Recurring transactions reduce manual entry for regular bills.
- Useful charts provide a clear overview of spending habits.
Cons
- Some advanced features may require a premium subscription.
- Manual entry can feel time-consuming for frequent card purchases.
- Bank synchronization availability may vary by country or institution.
- Limited collaboration options for managing shared household budgets.
- Learning all settings and tracking features may take some time.


